Life Insurance for Grandkids: How Grandparents Can Cover a Grandchild
How to Pick Homeowners Insurance: A Step-by-Step Guide
November 10, 2026
How to Change Your Homeowners Insurance Without a Coverage Gap
November 11, 2026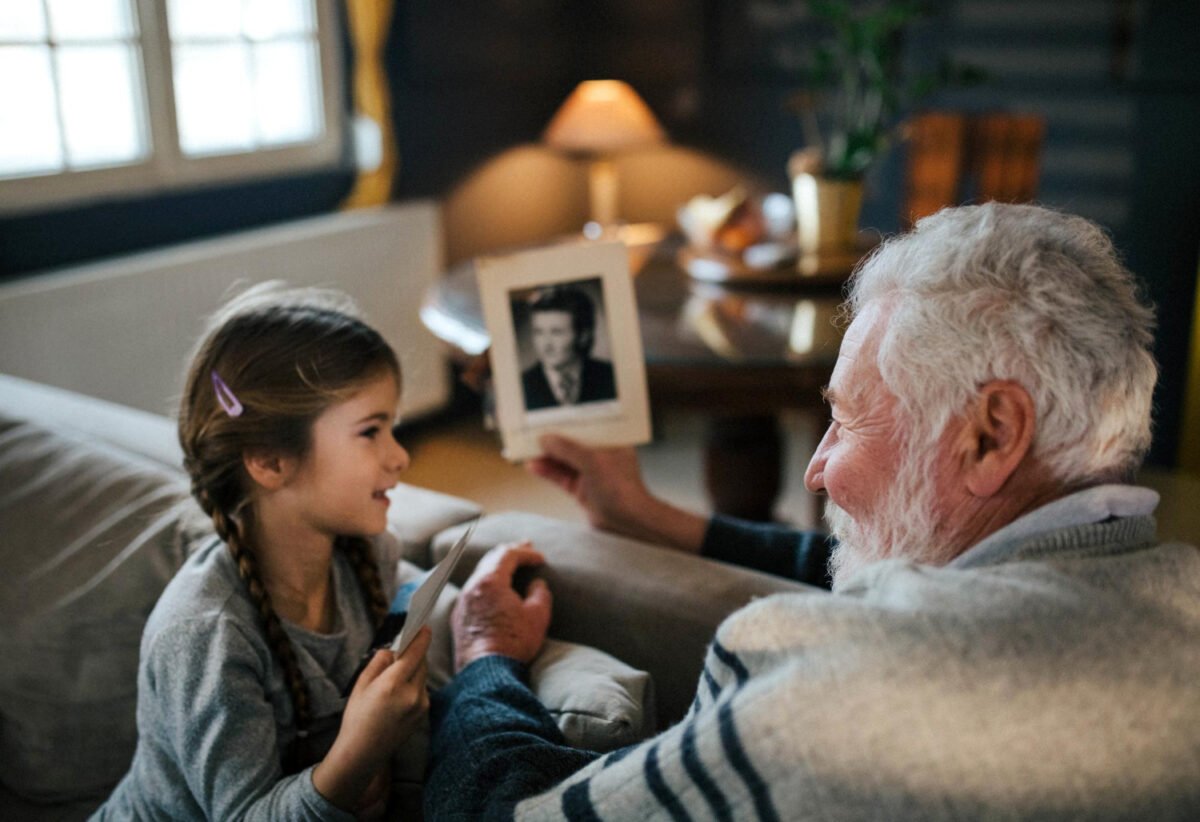
Life insurance for grandkids is usually a small whole life or term policy that a grandparent owns and pays for on a grandchild’s life. Most insurers require the parent or legal guardian’s written consent and proof that the grandparent has an insurable interest. Whole life policies can also build cash value the grandchild may use later.
It is a decision many grandparents consider when they want to do something lasting for a new grandchild. This guide explains how these policies work, who can buy them, how to think about cost, and the questions to ask before you apply.
How Does Life Insurance for Grandkids Work?
A life insurance policy has three roles: the owner, who controls and usually pays for the policy; the insured, whose life is covered; and the beneficiary, who receives the death benefit. When a grandparent buys a policy on a grandchild, the grandparent is normally the owner and payer, the grandchild is the insured, and the beneficiary is often a parent or the grandparent.
Policies for children are sometimes called juvenile life insurance. Coverage amounts are generally modest compared with adult policies, and many carriers use simplified applications with a few health questions about the child.
The main reasons grandparents buy this coverage are practical rather than financial:
- Locking in coverage early. A policy bought in childhood stays in force as long as premiums are paid, even if the grandchild’s health changes later.
- Building cash value. Permanent policies such as whole life can accumulate cash value over many years.
- Covering final expenses. A small death benefit can help a family with funeral and related costs in the rare event of a child’s death.
- Passing on a gift. Ownership can often be transferred to the grandchild as an adult.
Can a Grandparent Buy Life Insurance for a Grandchild?
In many cases, yes, but the rules depend on the state and the insurance company. Two requirements come up most often.
Insurable interest
Insurers require the owner to have an insurable interest in the insured person’s life, meaning a genuine family or financial relationship. Grandparents are often accepted, but some carriers limit grandparent-owned policies, for example when the child is not financially dependent on the grandparent, or require similar coverage on all minor grandchildren to avoid favouring one child.
Parent or guardian consent
Many states and insurers expect the parent or legal guardian to agree in writing. The Washington State Office of the Insurance Commissioner, for example, states that a grandparent must first get written consent from the child’s parent or legal guardian. Rules differ between states, so a licensed agent should confirm what applies where you live.
What Types of Policies Can Grandparents Buy?
| Option | How it works | Builds cash value? | Things to consider |
|---|---|---|---|
| Juvenile whole life policy | Permanent coverage on the child with fixed premiums | Yes, gradually | Higher premium than term; long-term commitment |
| Juvenile term policy | Coverage for a set number of years | No | Lower cost; ends when the term ends unless converted |
| Child rider on a parent’s policy | Adds child coverage to a parent’s own policy | No | Owned by the parent, not the grandparent; often convertible later |
Child riders are bought by parents on their own policies, so they are usually not an option for grandparents. If you want to understand how riders work in general, our guide to riders in final expense insurance policies explains the basics. For permanent coverage options, see our overview of whole life insurance.
How Much Life Insurance for Grandkids Do You Need?
There is no standard amount. Because children do not usually provide household income, the coverage is not meant to replace earnings. Families often think about:
- The likely cost of a funeral and related expenses.
- The premium the grandparent can comfortably keep paying for many years.
- Whether the goal is mainly a death benefit, mainly long-term cash value, or both.
- Any limits the insurer sets on child coverage, which can depend on the parents’ own coverage.
Illustrative example, assumptions stated: a grandparent wants to cover likely funeral costs and leave a small policy the grandchild can take over at adulthood. They compare a juvenile whole life policy with a modest face amount against a lower-cost term policy, and choose the whole life option because they can afford the fixed premium and value the cash value. This is a hypothetical scenario; real quotes depend on the child’s age and health, the state, the carrier and the amount chosen.
What Happens to the Policy When the Grandchild Grows Up?
Because the grandparent owns the policy, they control it until they choose to change that. Common paths include:
- Transferring ownership to the grandchild once they are an adult, so they can keep paying and use the coverage or cash value.
- Naming a successor owner, such as a parent, so the policy continues if the grandparent dies first.
- Using the cash value of a whole life policy through policy loans or withdrawals, which can reduce the death benefit.
- Letting a term policy end or converting it, if the policy allows conversion.
Transfers of ownership and cash value can have tax consequences. Talk to a tax professional before you transfer a policy or take money from it.
What Should Grandparents Check Before Applying?
- Talk to the parents first. Agree on the purpose of the policy and get their written consent.
- Confirm your state’s rules. A licensed agent can check insurable interest and consent requirements.
- Compare policy types. Decide between whole life and term based on your goals and budget.
- Check affordability for the long term. Missing premiums can cause a policy to lapse.
- Name a successor owner. Plan who will own the policy if you die before transferring it.
- Read the policy illustration. Ask which values are guaranteed and which are not.
- Keep records together. Store the policy and contact details where the family can find them.
If you are also thinking about your own coverage, our guide to child insurance options and our final expense resources can help you plan for the whole family.
What Mistakes Should You Avoid?
- Buying without the parents’ knowledge or agreement.
- Treating cash value as a guaranteed savings or college fund; growth depends on the policy’s terms.
- Choosing a premium that is hard to sustain on a fixed retirement income.
- Forgetting to name a successor owner and contingent beneficiary.
- Assuming every insurer will accept a grandparent as owner.
Frequently Asked Questions
Can grandparents get life insurance on grandchildren without parental consent?
Often not. Many insurers and some state regulators expect written consent from the child’s parent or legal guardian before a grandparent can own a policy on the child. Requirements vary by state and carrier, so ask a licensed agent to confirm the rules that apply in your state before you apply.
Is whole life or term better for a grandchild?
Neither is right for everyone. Whole life offers permanent coverage and builds cash value but costs more. Term costs less but ends after a set period unless it can be converted. Choose based on whether you want lasting coverage and cash value, and on the premium you can keep paying.
Can I transfer the policy to my grandchild later?
Usually, yes. Many policies allow the owner to transfer ownership to the insured once they are an adult. The grandchild can then pay premiums and control the policy. Ownership transfers can have tax implications, so check with a tax professional and the insurer before making the change.
Does a grandchild’s policy pay for college?
A life insurance policy is not designed as a college fund. A whole life policy may build cash value that can be borrowed or withdrawn, but doing so can reduce the death benefit, and growth depends on the policy’s terms. Compare it with dedicated education savings options with a financial professional.
Who should be the beneficiary of a grandchild’s policy?
Beneficiaries are commonly a parent or the grandparent who owns the policy. Name a contingent beneficiary as well, and review the choice when family circumstances change. A licensed agent can explain how beneficiary choices interact with ownership and what happens if the owner dies first.
Conclusion
Life insurance for grandkids can lock in coverage early, build cash value with a whole life policy, and give a grandchild a lasting gift. Before you apply, talk to the parents, confirm insurable interest and consent rules in your state, compare whole life and term, keep premiums affordable and plan who will own the policy later.
This article is for general information only and is not insurance, legal or tax advice. Coverage, eligibility and prices vary by state, carrier and individual circumstances.
Ready to explore options for your family? Contact FE Life Insurance to speak with a licensed agent and request a free, no-obligation quote.
